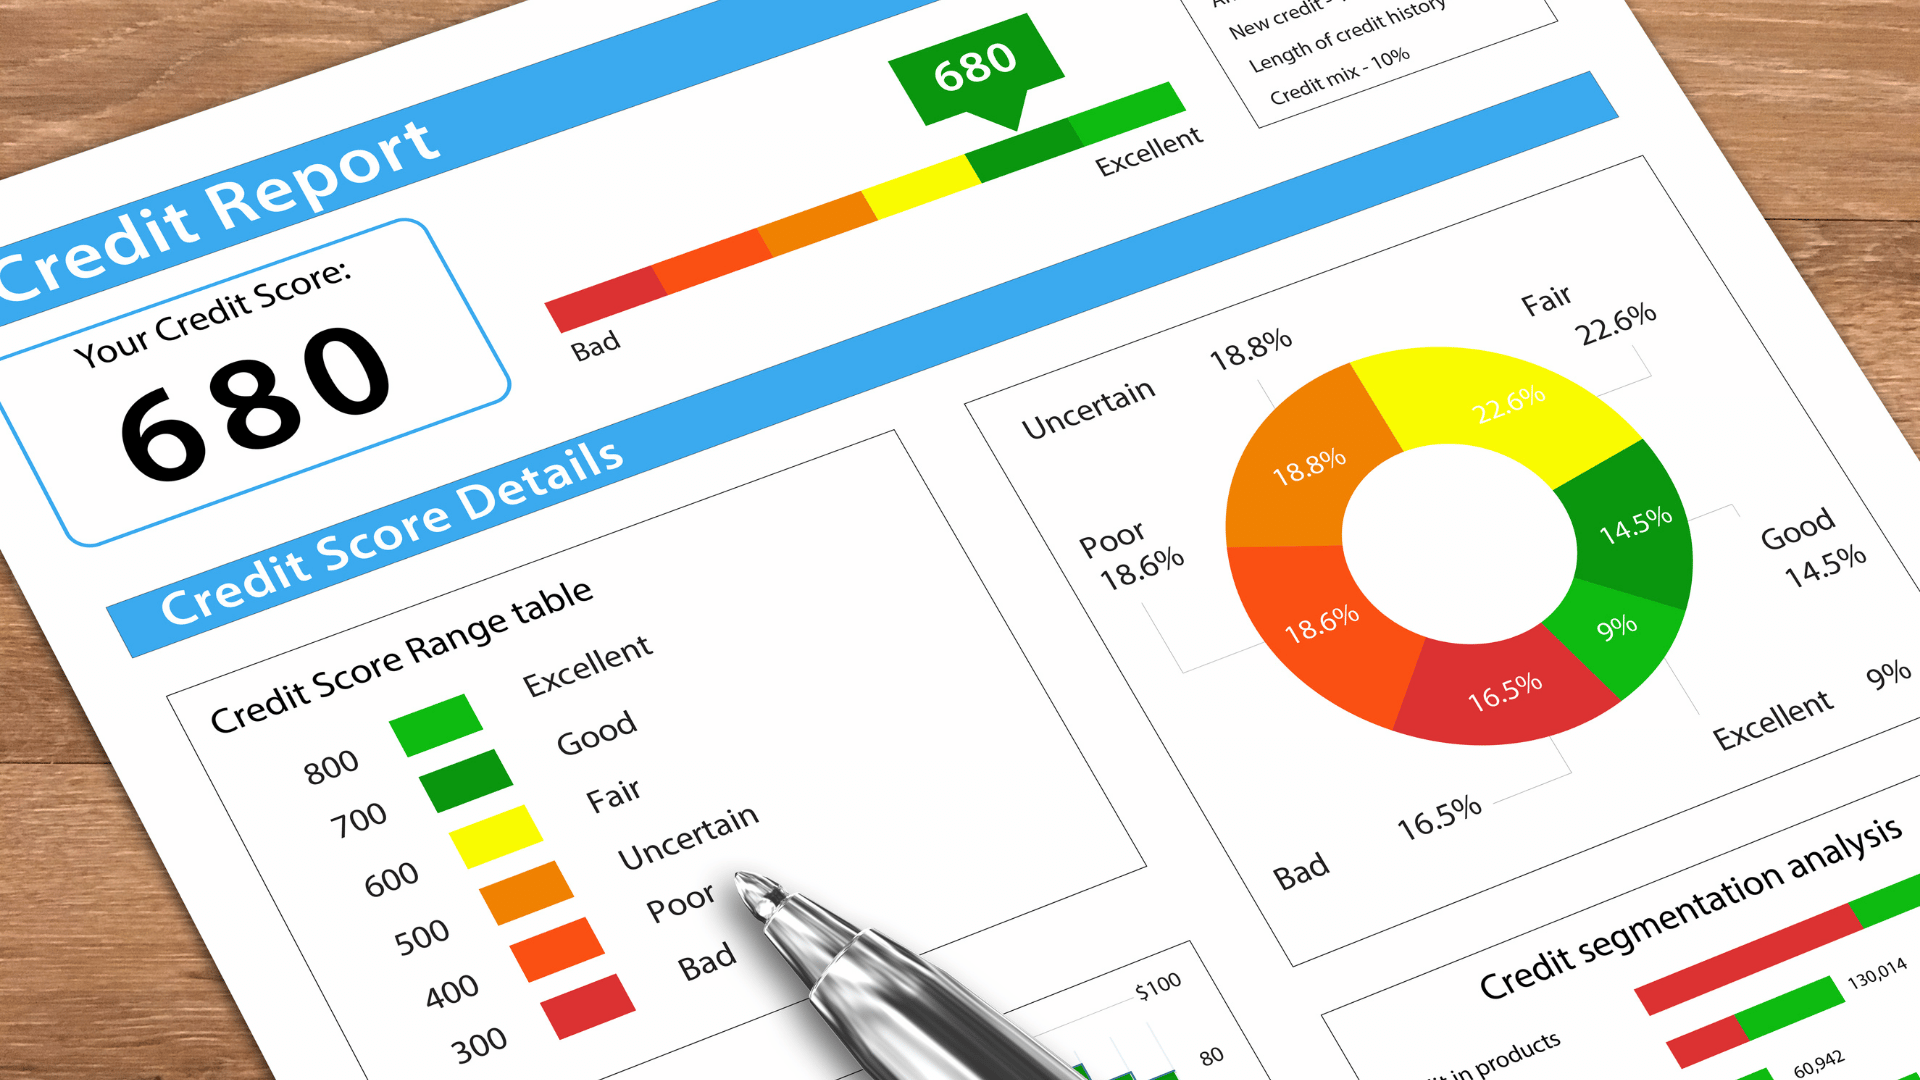
Your credit report can affect so many different aspects of your life. This includes everything from jobs and houses to cars and insurance. Because of these stakes, a mistake on your report can create real problems.
The frustrating part is that many people don’t find these errors until they’re already trying to get approved for something important. Then, they learn their credit score is lower than it should be because of information that may not even be correct.
The good news is that you have rights. The Fair Credit Reporting Act, also known as the FCRA, is a federal law that helps protect the accuracy, fairness, and privacy of information in consumer reports. If your report contains inaccurate or incomplete information, you generally have the right to dispute it and ask for an investigation. A consumer rights lawyer can help you do this.
In the meantime, here are seven common credit reporting errors to watch for:
1. Wrong Personal Information
Some credit report errors are as simple as having incorrect personal information. For example, your report may show the wrong name, a misspelled name, an old address, or the wrong date of birth. At first, this may not seem like a major problem. But incorrect personal information can point to a bigger issue.
It may mean your credit file has been mixed with someone else’s. Or it could also be a sign that an account was opened with your information. If you see a strange address, phone number, or name variation, don’t ignore it. This could create massive problems later on (if it hasn’t already).
2. Accounts That Don’t Belong to You
One of the most serious credit reporting errors is an account you never opened. This can happen because of identity theft, a mixed file, or a reporting mistake. You may see a credit card, loan or collection account that you don’t recognize. If that account has late payments or collection activity, it can hurt your credit quickly.
Don’t assume it’s just a harmless mistake. An account that doesn’t belong to you can affect your score and make lenders question your risk when you apply for credit.
If you believe identity theft is involved, you may need to take extra steps, such as placing a fraud alert or filing an identity theft report.
3. Incorrect Payment History
Payment history is one of the most important parts of your credit profile. That’s why a late payment error can be so damaging.
Your report may show that you paid late even though you paid on time. Or it may list an account as delinquent after you brought it current. Errors like these matter. Lenders want to know whether you pay as agreed. A wrongly reported late payment can make you look less reliable than you are.
If you see this kind of error, gather proof. You’ll need to be able to explain which month is incorrect, what the report says, and what the correct information should be.
4. Incorrect Balances or Credit Limits
Credit reports may also show the wrong balance or credit limit on an account.
This can be a problem because credit scoring models often look at how much of your available credit you’re using. If your credit card balance is reported too high, or your limit is reported too low, it can make it look like you’re using more credit than you really are.
For example, suppose your card has a $5,000 limit and a $1,000 balance. That looks very different from a report showing a $1,000 limit and a $1,000 balance. In the second case, it looks like the card is maxed out, even if that’s not true.
Check balances, credit limits, and account status together. A small reporting mistake can make your credit profile look riskier than it really is.
5. Duplicate Collection Accounts
Collection accounts are stressful enough when they’re reported once. Sometimes, the same debt appears more than once.
This may happen when a debt is sold or transferred from one collector to another. The old collector may still appear, and the new collector may appear too. In some cases, the same debt may look like two separate debts, making your report seem worse.
If you see two collection accounts that appear to come from the same original debt, compare the details. Look at the original creditor and information. If the same debt is being reported in a way that is inaccurate or misleading, you can dispute it.
Take Care of Your Credit
Credit is like a newborn baby. It needs to be cared for and nurtured so that it can grow into something healthy and productive. The reality is that credit reporting errors are more common than many people realize.
By staying alert and checking your credit reports on a regular basis, you can give yourself a better chance to identify errors early and take the proper steps.