You’ve probably heard a lot about blockchain technology lately, and maybe it sounds a bit confusing. It’s a pretty big deal, and understanding how blockchain technology works is becoming more important. Think of it like a super secure digital notebook that’s shared among many people. This guide is here to break down the basics, showing you how it all fits together without getting lost in complicated tech talk. We’ll look at what it is, how it keeps things safe, and why it matters beyond just digital money.
Key Takeaways
- Blockchain is like a shared digital ledger spread across many computers, making it very hard to tamper with.
- Information is stored in ‘blocks’ that are linked together in a ‘chain’, creating a historical record.
- The network of computers must agree on new information before it’s added, a process known as consensus.
- This technology has uses far beyond cryptocurrencies, such as tracking goods and securing records.
- While secure, blockchain faces challenges like speed and privacy that are being worked on.
Understanding The Core Of Blockchain Technology
What Is A Blockchain In Simple Terms?
Imagine a digital notebook that’s shared among many people. Every time someone adds a new entry, everyone gets a copy, and it’s nearly impossible to go back and change an old entry without everyone noticing. That’s the basic idea behind blockchain. It’s a way to record information, like transactions, in a way that’s transparent and very hard to tamper with. Instead of one person or company holding all the records, the information is spread out across a network of computers. This makes it a secure and trustworthy system for keeping track of things, whether it’s digital money or other types of data. It’s a system built on shared trust, rather than relying on a single authority. This technology isn’t just for digital money; it can be used for tracking goods, verifying identities, and more.
The Decentralized And Distributed Nature Of Blockchain
One of the most talked-about features of blockchain is its decentralized and distributed nature. Unlike traditional systems where data lives in one central place, like a bank’s server, a blockchain spreads its data across many computers, called nodes, in a network. This means there’s no single point of failure. If one computer goes offline, the network keeps running. This distribution is key to its resilience and security. It’s a fundamental shift in how we can record and trust information.
How Blockchain Keeps Information Safe
Blockchain uses special codes, like digital fingerprints, to lock up information. Each new piece of information is linked to the one before it, creating a chain. If someone tries to change something, the code breaks, and everyone on the network knows it’s not right. This makes it very hard to cheat the system. The security comes from a combination of cryptographic hashing and the distributed nature of the ledger. Every transaction is verified by multiple participants before being added to a block, and each block is cryptographically linked to the previous one. This creates a tamper-evident record that is incredibly difficult to alter retroactively. The security model is built into the very structure of the chain, making it a robust solution for data integrity. This is why many see it as a secure way to manage sensitive information, similar to how cryptocurrency stocks are secured by complex algorithms.
The core strength of blockchain lies in its ability to create a shared, immutable record without needing a central authority to vouch for its accuracy. This distributed trust model is what sets it apart from traditional databases.
The Anatomy Of A Blockchain
When we talk about blockchain, we’re really talking about a specific way of organizing and linking data. It’s not just a jumble of information; it’s structured in a very particular way to ensure security and transparency. Think of it like building with digital LEGO bricks, where each brick has a specific purpose and connects to the next in a predictable order.
What A Block Contains
At its core, a blockchain is made up of individual units called ‘blocks’. You can picture each block as a page in a digital ledger. What goes on this page? Primarily, it’s a collection of verified transactions. These aren’t just random entries; they are the actual data being recorded – perhaps details of who sent what to whom, or any other information the blockchain is designed to track. Alongside these transactions, each block also carries a unique digital fingerprint, known as a ‘hash’. This hash is generated based on all the data within that specific block. If even a tiny detail within the block is altered, its hash changes completely, making any tampering immediately obvious.
How Blocks Are Chained Together
The ‘chain’ part of blockchain is where the real security magic happens. Each new block created doesn’t just contain its own unique hash; it also includes the hash of the block that came immediately before it. This creates a chronological link, like a digital thread connecting one block to the next in a sequence. So, Block 2 contains the hash of Block 1, Block 3 contains the hash of Block 2, and so on. This sequential linking is what forms the chain.
- Block 1: Contains its data and its hash.
- Block 2: Contains its data, its hash, and the hash of Block 1.
- Block 3: Contains its data, its hash, and the hash of Block 2.
- …and so forth.
The Role Of Cryptographic Hashes
Cryptographic hashes are the unsung heroes of blockchain security. They are mathematical functions that take an input (the data within a block) and produce a fixed-size string of characters – the hash. This hash is unique to the input data. Even a minor change to the input will result in a completely different hash. This property is vital. When a new block is added, it includes the hash of the previous block. If someone tries to tamper with an older block, its hash will change. Because the subsequent block contains the original hash of that tampered block, the link will break, and the network will immediately detect the inconsistency. It’s this chain of hashes that makes the blockchain so resistant to alteration. Trying to change a block would require recalculating the hashes for that block and every single block that follows it, a task that becomes practically impossible on a large, distributed network. This intricate linking is a key reason why blockchain technology is considered so secure for recording transactions, similar to how investment banking compensation is meticulously tracked.
The interconnectedness of blocks, secured by unique cryptographic hashes, creates a tamper-evident ledger. Any attempt to alter past data would break the chain, signaling a breach to all participants on the network.
How Blockchain Works In Practice
So, we’ve talked about what blockchain is and its basic structure. Now, let’s get into the nitty-gritty of how it actually functions when new information is added. It’s a process that relies on network agreement and creates a permanent record.
The Process Of Adding Transactions
When someone wants to add new information to the blockchain – let’s say a transaction, like sending digital currency or updating a record – it doesn’t just appear out of nowhere. First, this proposed transaction is broadcast to a network of computers, often called nodes. These nodes are the participants in the blockchain network. They all receive a copy of the proposed transaction and begin the process of checking its validity. This validation step is pretty important; it makes sure the transaction follows the rules of the network. For example, in a cryptocurrency blockchain, a node would check if the sender actually has the funds they’re trying to send.
Achieving Network Consensus
Once transactions are validated by individual nodes, they need to be grouped together and officially added to the blockchain. This is where the concept of "consensus" comes in. Think of it as the network collectively agreeing on what’s true. Different blockchains use different methods to reach this agreement, but the goal is the same: to ensure that everyone on the network agrees on the order and validity of transactions before they are permanently recorded. This agreement process is what prevents fraudulent or conflicting transactions from being added.
- Proof-of-Work (PoW): Nodes (often called miners) solve complex mathematical puzzles. The first one to solve it gets to propose the next block of transactions, and their solution is easily verifiable by others. This requires significant computing power.
- Proof-of-Stake (PoS): Validators are chosen to create new blocks based on the amount of cryptocurrency they "stake" or hold. The more they stake, the higher their chance of being selected. This method generally uses less energy than PoW.
- Delegated Proof-of-Stake (DPoS): Token holders vote for delegates who are then responsible for validating transactions and creating new blocks. This can lead to faster transaction times.
The consensus mechanism is the backbone of blockchain security and integrity. It’s the process that allows a decentralized network to function as a single, trustworthy source of truth without needing a central authority to dictate it.
The Immutable Nature Of The Chain
After a block of validated transactions is agreed upon by the network through consensus, it’s added to the existing chain. Each new block contains a cryptographic hash of the previous block, creating a secure link. This linkage is what makes the blockchain "immutable" – meaning it’s extremely difficult to alter or delete past records. If someone were to try and tamper with a transaction in an old block, its hash would change. Because that hash is recorded in the next block, the link would break, and the entire network would immediately recognize that something is wrong. This chain reaction of verification and linkage is what gives blockchain its tamper-proof quality.
Here’s a simplified look at how blocks are chained:
- Transaction Validation: Individual nodes verify proposed transactions.
- Block Creation: Validated transactions are bundled into a new block.
- Consensus Reached: The network agrees on the validity and order of the new block.
- Block Appending: The new block, containing the hash of the previous block, is added to the end of the chain.
- Immutability: The chain is now updated across all nodes, making past records permanent.
Exploring Blockchain Use Cases Beyond Cryptocurrencies
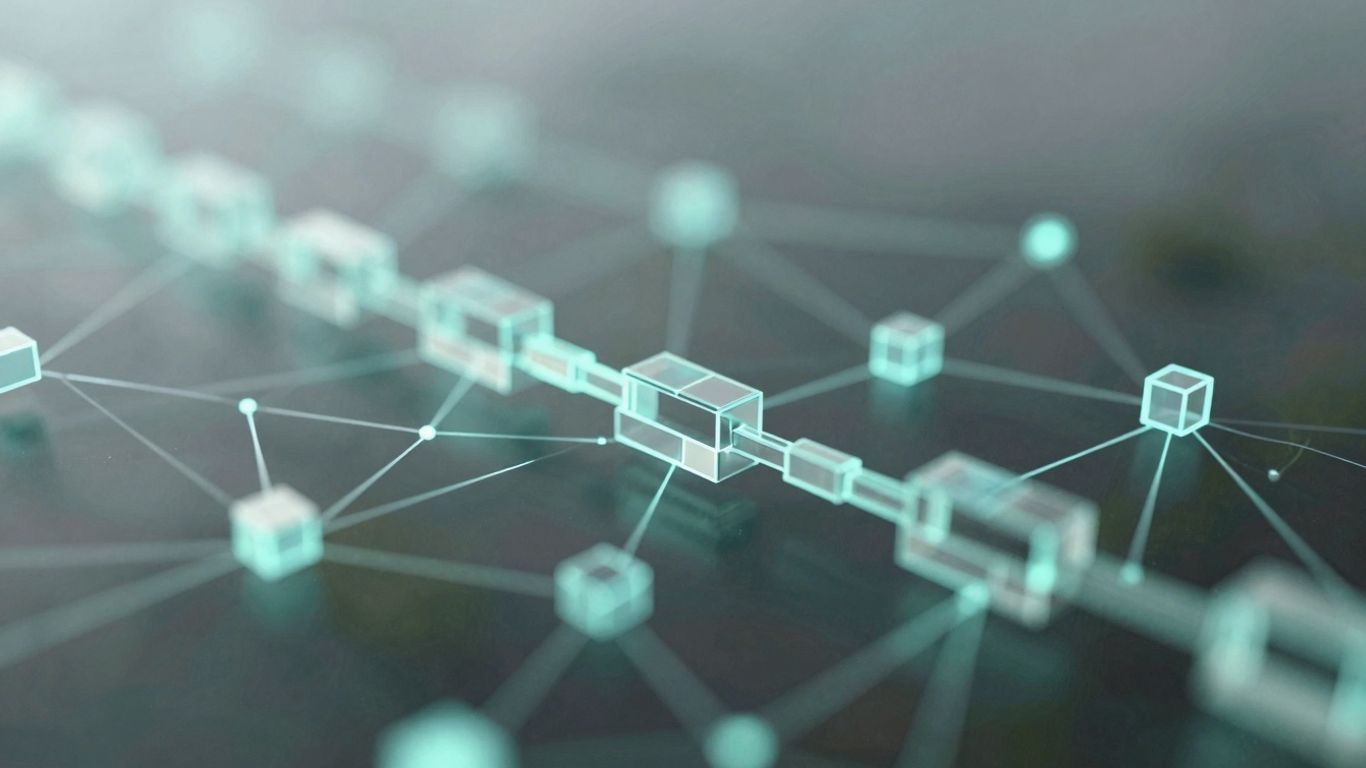
While cryptocurrencies like Bitcoin often grab the headlines, the real power of blockchain technology lies in its ability to reshape many other industries. Think of it as a secure, transparent, and shared digital notebook that can record almost anything of value. This makes it incredibly useful for tracking, verifying, and managing information in ways we haven’t seen before.
Revolutionizing Supply Chain Management
Imagine trying to track a product from the farm or factory all the way to your doorstep. It’s a complex journey with many hands involved, and it’s easy for things to get lost, faked, or mishandled. Blockchain can change this by creating a single, shared record of every step. Each time a product moves, is inspected, or changes hands, that event can be recorded on the blockchain. This means everyone involved – from the farmer to the shipping company to the retailer – can see the same, up-to-date information. This level of transparency helps prevent counterfeit goods from entering the market and ensures that products are handled correctly. This shared ledger builds trust and accountability across the entire supply chain.
Here’s a simplified look at how it works:
- Origin Tracking: Recording where raw materials come from.
- Movement Logs: Documenting each transfer and location change.
- Quality Checks: Stamping approvals and certifications.
Enhancing Healthcare Records
Keeping patient data secure and accessible is a major challenge. Traditional systems can be vulnerable to breaches, and sharing records between different providers can be slow and complicated. Blockchain offers a solution by creating an incorruptible, decentralized, and transparent log of all patient information. Medical institutions can use this technology to securely share patient records while maintaining strict privacy controls. This means your medical history can be accessed by authorized doctors quickly and safely, no matter where you are.
Blockchain’s ability to maintain an unalterable record of data makes it ideal for sensitive information like health records, where accuracy and security are paramount.
Securing Digital Identities
In today’s digital world, managing our identities online can be tricky. We often rely on central authorities to verify who we are, which can lead to data silos and security risks. Blockchain provides a way for individuals to control their own digital identities. This means you can manage your personal credentials and decide exactly who gets to see what information, without needing a third party. It’s a step towards self-sovereign identity, giving you more control over your personal data and how it’s used. This technology is also being explored for secure online voting systems and managing access to digital resources, making online interactions more trustworthy. For more on securing digital assets, understanding how your cloud storage works is important cloud data.
Blockchain is not just for cryptocurrencies; its applications in supply chain management, healthcare, and digital identity are transforming how we interact with information and each other.
Navigating Challenges And Security In Blockchain
While blockchain technology offers some really neat advantages, it’s not without its own set of problems and security worries. Understanding these is pretty important if you want to get a good grasp on how it actually works and where it might fall short.
The Scalability Debate
One of the biggest headaches people talk about is scalability. Imagine a really popular highway during rush hour – when too many cars try to get on at once, everything grinds to a halt. Blockchain can face a similar issue. As more and more transactions get added to the network, processing them can become slower and, you guessed it, more expensive. Different blockchain projects are trying out various fixes for this, but finding a solution that works for everyone, especially for big companies that need to handle tons of transactions super fast, is still a work in progress. It’s a bit like trying to fit the entire population of a city onto a single country road.
Security Concerns And Mitigation Strategies
Blockchain gets a lot of praise for being secure, mostly because of its fancy cryptography and how it’s spread out across many computers. But, it’s not completely immune to trouble. For example, there’s the idea of a "51% attack." This is where one person or group could theoretically gain control of more than half of the network’s computing power. If that happened, they could potentially mess with transactions. To stop things like this, networks use strong ways to agree on what’s valid (called consensus mechanisms) and encourage lots of people to join in. Keeping the network spread out is one of the best defenses against one single point of failure. Other security steps include:
- Using really strong encryption for data.
- Writing code for smart contracts very carefully.
- Constantly checking the network for anything that looks suspicious.
It’s important to remember that blockchain isn’t a magic bullet for every problem. While it offers unique advantages in transparency, security, and decentralization, its implementation requires careful thought about potential drawbacks like transaction speed, energy use, and the evolving regulatory landscape. A clear-eyed view of these challenges helps in identifying where blockchain can truly add value.
Privacy Considerations On The Blockchain
Even though transactions on many blockchains are out in the open for everyone to see, this transparency can sometimes clash with the need for privacy. Every single transaction gets written down on a public ledger. If not handled carefully, this could show patterns or connections that people might not want revealed. To deal with this, smart folks are developing and using techniques like zero-knowledge proofs. These allow for checking that something is valid without actually showing the private details. It’s a tricky balance between being open and needing to keep personal or business information safe. This technology is still evolving, and understanding its potential for cryptocurrency investments is just one piece of the puzzle.
Common Misconceptions About Blockchain
When you first hear about blockchain, it’s easy to get caught up in the hype and develop some pretty wild ideas about what it is and what it can do. Let’s clear the air and tackle some of the most common misunderstandings that seem to pop up.
Is Blockchain Only For Illegal Activities?
This is a persistent myth, likely fueled by early news stories about cryptocurrencies being used for illicit purposes. While it’s true that some bad actors have used blockchain-based currencies to try and hide their tracks, that’s far from the whole story. Think of it like cash – it can be used for illegal things, but that doesn’t make the money itself bad or its primary purpose illegal. Most of the blockchain world is focused on legitimate uses, like making supply chains more transparent or securing digital identities. The vast majority of blockchain applications are designed for legitimate and beneficial purposes.
Understanding Blockchain Anonymity
Another common idea is that blockchain offers complete anonymity. This isn’t quite right. While transactions on a blockchain are often pseudonymous (meaning they’re linked to a digital wallet address, not directly to your name), they aren’t truly anonymous. Every transaction is recorded on a public ledger that anyone can see. If someone can link that wallet address back to you, then your transaction history becomes visible. It’s more about privacy and transparency than hiding who you are completely.
Here’s a quick look at how some common misconceptions stack up:
- Myth: Blockchain is only for illegal activities.
Reality: Legitimate uses far outweigh illicit ones. - Myth: Blockchain transactions are completely anonymous.
Reality: Transactions are pseudonymous and publicly viewable. - Myth: You need to be a tech expert to use blockchain.
Reality: User-friendly applications are becoming widespread.
Blockchain Is Not Just For Tech Experts
Some folks think you need to be a coding wizard or a finance guru to understand or use blockchain. That used to be more true, but things have changed a lot. Many applications built on blockchain technology now have user-friendly interfaces that are as simple to use as any other app on your phone or computer. You don’t need to understand the intricate details of cryptography to send a cryptocurrency payment or interact with a decentralized application.
It’s important to remember that blockchain is a tool, and like any tool, its impact depends on how it’s used. Focusing solely on the negative or the most sensational aspects misses the broader picture of its potential benefits and everyday applications.
The Potential Impact On Industries Worldwide
Blockchain technology is more than just a buzzword; it’s a foundational shift that’s starting to reshape how various industries operate. Think about it: a system that allows for secure, transparent, and decentralized record-keeping can solve a lot of old problems. It’s not just about digital currencies anymore. We’re seeing real-world applications emerge that could fundamentally change how businesses function and how we interact with information.
Transforming Business Operations
Many businesses are looking at blockchain to streamline their processes. For instance, in finance, cross-border payments that used to take days and cost a lot can now be settled in minutes with significantly lower fees. Imagine a supply chain where every step, from raw material to finished product, is recorded on an immutable ledger. This means you can instantly verify the authenticity of goods, track their origin, and cut down on counterfeiting. It’s about building trust and efficiency into the very fabric of operations.
Creating New Opportunities
This technology is also opening doors to entirely new business models and services. Decentralized finance (DeFi) is a prime example, offering financial services without traditional intermediaries. We’re also seeing the rise of "smart contracts" – self-executing agreements written in code. These contracts automatically enforce terms when certain conditions are met, reducing the need for lawyers or brokers in many transactions, from real estate to insurance claims. The potential for innovation here is vast, leading to more direct and efficient interactions.
The Future Of Decentralized Systems
As blockchain matures, its influence is expected to grow. We’re seeing trends like the integration of blockchain with artificial intelligence to create smarter, more secure systems. Furthermore, as regulatory frameworks become clearer, more large organizations are moving beyond pilot projects to full-scale implementations. This indicates a growing confidence in the technology’s ability to deliver tangible benefits. The shift towards more sustainable consensus mechanisms also addresses earlier concerns about energy consumption, making blockchain a more viable option for widespread adoption.
The core advantage of blockchain lies in its ability to create a shared, tamper-proof record of transactions and data. This distributed trust mechanism can reduce reliance on central authorities, streamline complex processes, and introduce new levels of transparency and security across diverse sectors.
Wrapping Up Our Blockchain Journey
So, we’ve walked through what blockchain is all about, from its basic building blocks to how it all connects. It’s not just about digital money; it’s a new way to handle information securely and transparently. We’ve seen how it works, why it’s different from what we’re used to, and where it might take us. While there are still hurdles to clear, like making it faster and more energy-efficient, the potential for blockchain to change how we do business and interact online is pretty clear. Keep an eye on this space – it’s still early days, and there’s a lot more to come.
Frequently Asked Questions
What is blockchain in simple terms?
Imagine a digital notebook shared among many people. Every time someone adds a new entry, everyone gets a copy, and it’s very hard to change old entries without everyone noticing. This makes it a secure and open way to keep track of information, like transactions.
How does blockchain keep information safe?
Blockchain uses special codes, like digital fingerprints, to lock information. Each new piece of information is linked to the one before it, creating a chain. If someone tries to change something, the code breaks, and everyone on the network knows it’s not right, making it very difficult to cheat.
Is blockchain only used for cryptocurrencies like Bitcoin?
No, while Bitcoin was the first major use, blockchain is used for much more. It can help track products from where they come from, keep important records safe, and even make voting systems more trustworthy. It’s a technology that can help in many different areas.
Are blockchain transactions completely anonymous?
Not entirely. While transactions are often linked to a digital wallet address instead of a real name, they aren’t fully secret. Every transaction is recorded on a public list that anyone can see. If someone can connect that wallet address to you, your transaction history can become visible.
Can blockchain handle a lot of information at once?
This is a challenge that people are working on. Sometimes, the system can get slow if too many people try to add information at the same time. Engineers are developing new ways to make blockchain faster and handle more transactions, like improving a busy road.
Do I need to be a computer expert to understand blockchain?
You don’t need to be a computer whiz! While the technology can be complex, many apps are being made to make it easy for everyday people to use and understand. It’s similar to how many people use smartphones without knowing all the technical details.