The Insurance Adjuster’s First Call: What Nashville Drivers Get Wrong Before They Hire Anyone
Most people believe the worst part of a car crash is the sound of metal folding. It isn’t. It’s the phone call forty minutes later, when a friendly voice asks how you’re feeling and you answer honestly because nobody told you not to.
That answer goes into a file. So does the one you give the second time, and the third. Insurance adjusters aren’t villains for recording it. They’re doing a job, and the job is to pay you as little as the file will allow. You’re doing a job too, whether you realize it or not. Your job starts the second you hang up.
Here’s the part that surprises people: you don’t need a lawyer on day one to protect yourself. You need to stop handing out free information. That’s the whole game in the first seventy-two hours, and it’s why so many Nashville drivers end up calling Nashville auto accident attorneys weeks later with a claim that’s already been quietly devalued.
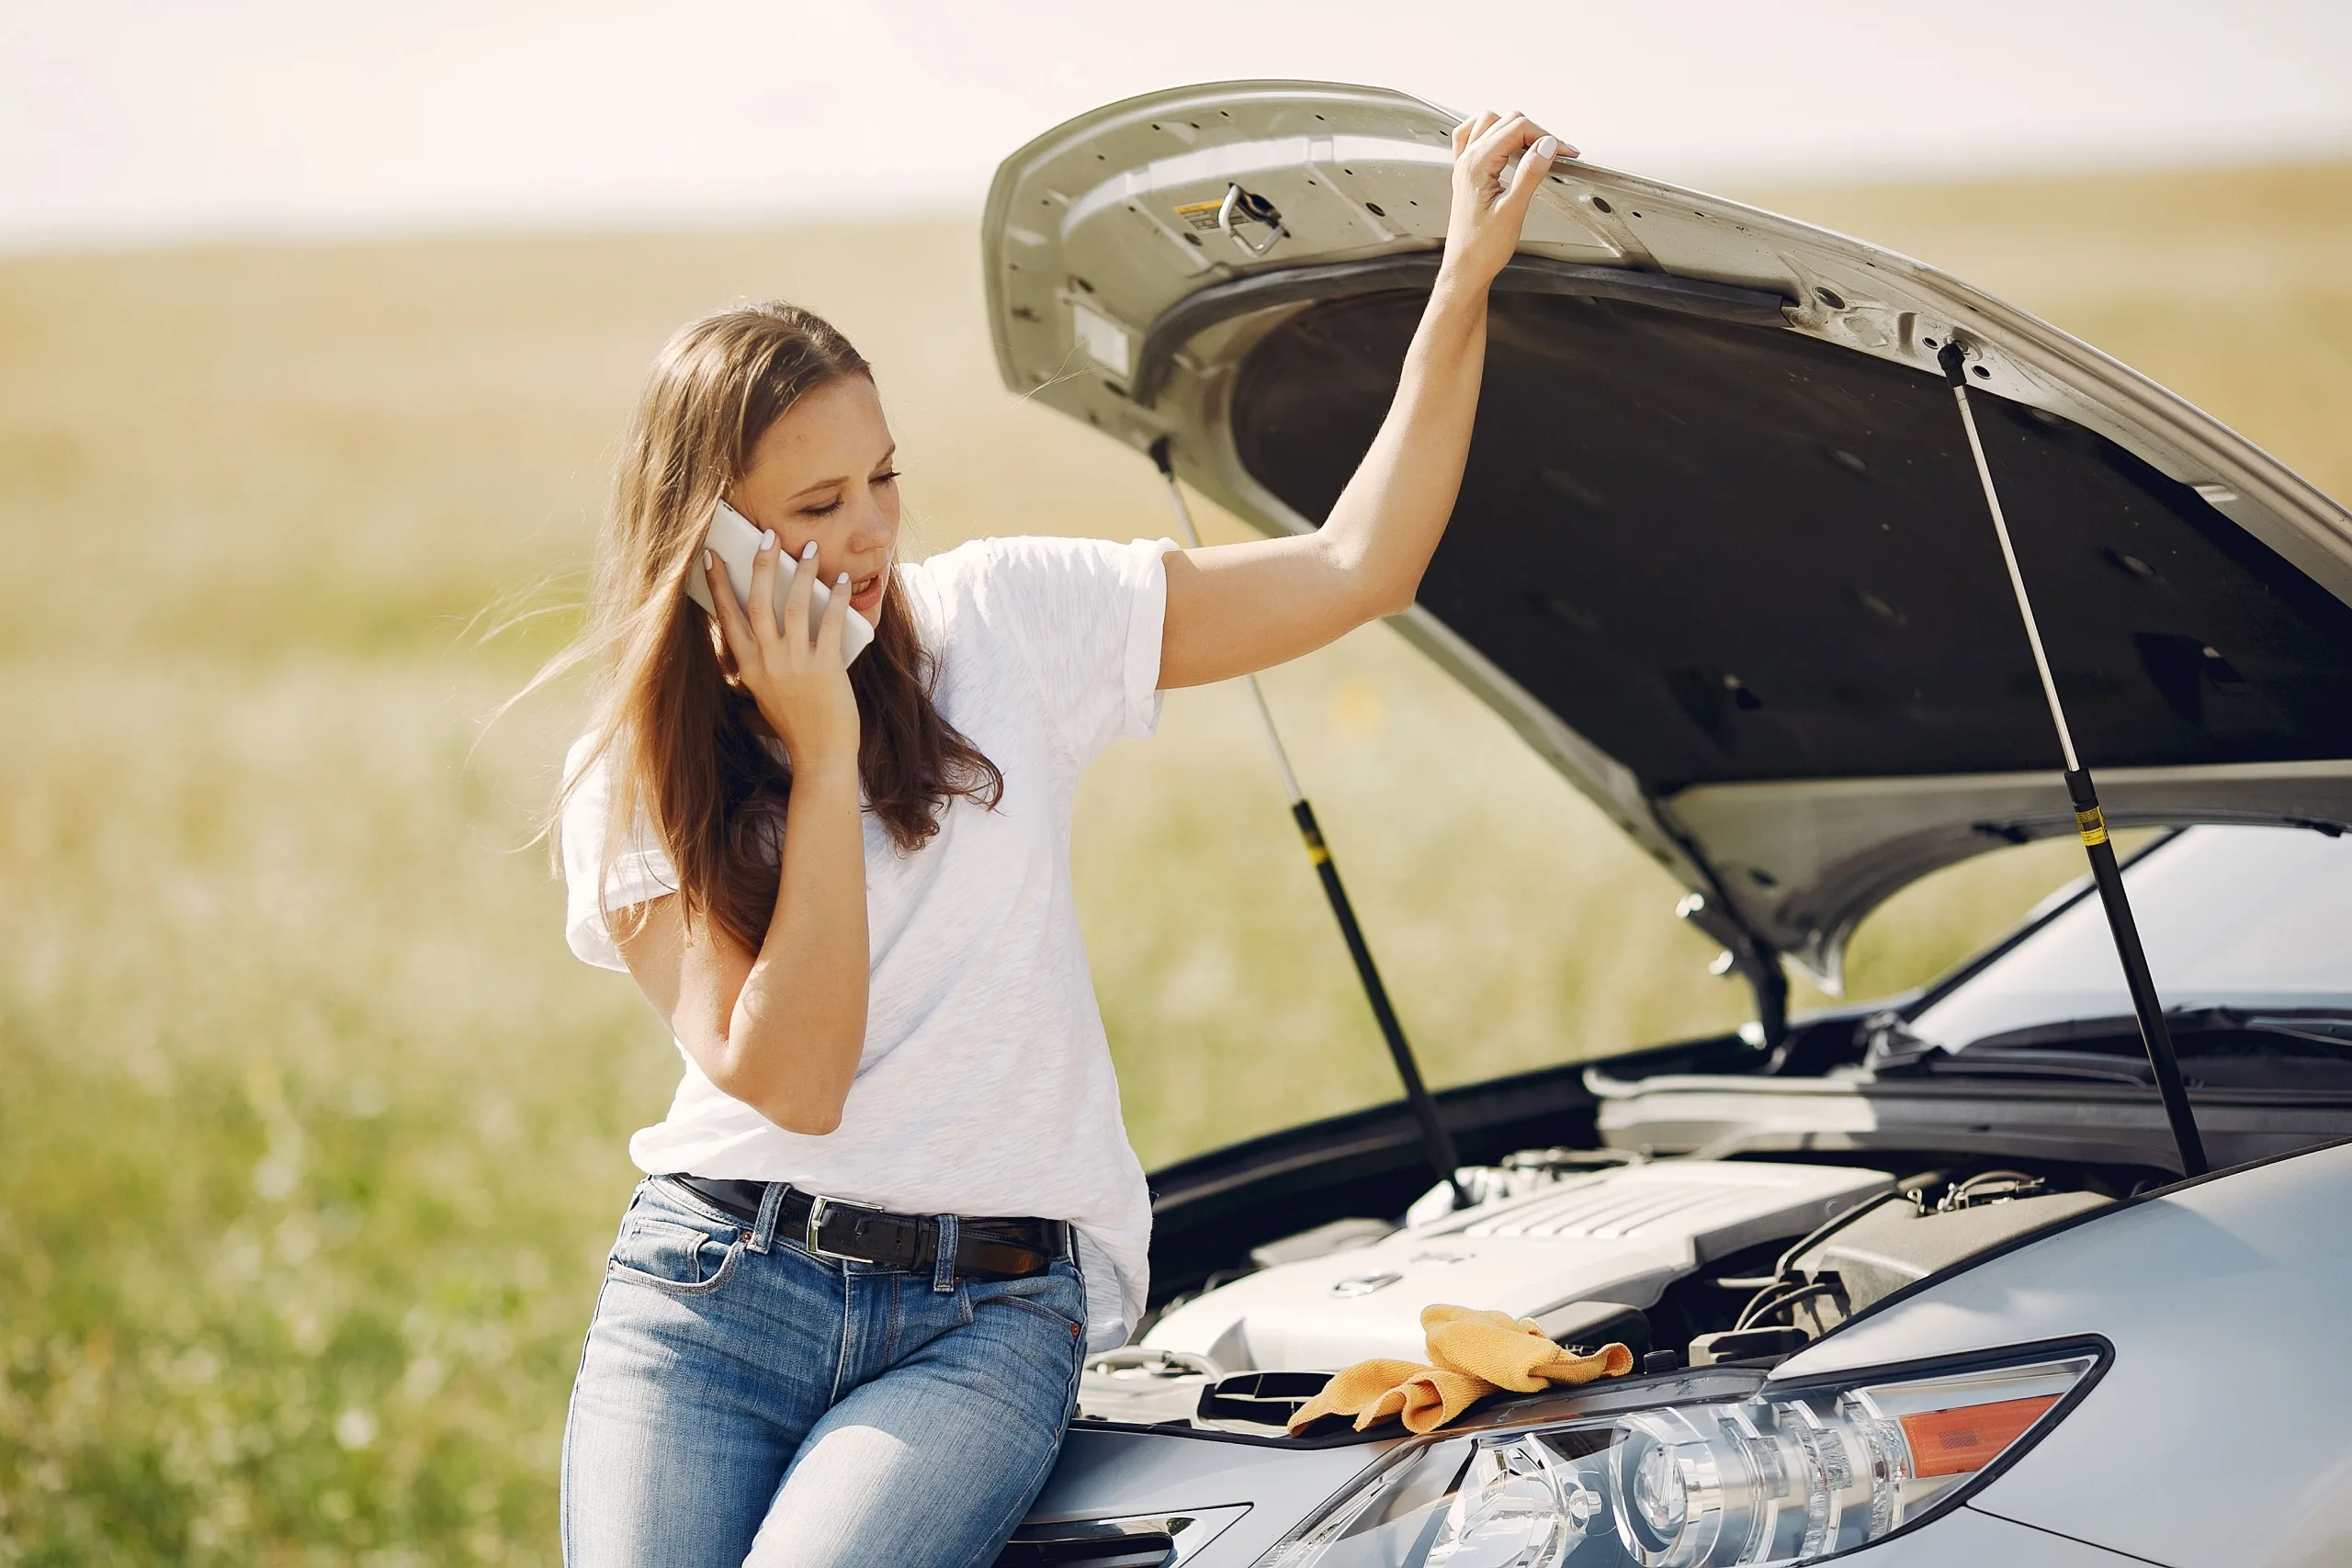
What actually happens on the first call
The adjuster introduces themselves, expresses concern, and asks a few questions that sound like small talk. Were you on your way to work? How fast were you going? Did you see them coming? Have you been to a doctor yet?
Every one of those has a second purpose. “On your way to work” touches wage loss and whether a commercial policy might be in play. “How fast were you going” invites a number you’ll have to defend later. “Did you see them coming” is fishing for a reaction-time admission. “Have you been to a doctor” tests whether there’s a documented injury to pay for, and if the answer is no, the adjuster now knows your claim has a soft spot.
You are not required to answer any of it on the spot. You can say you’re shaken up, you’re going to see a doctor, and you’ll follow up. Then do exactly that. I’d take a polite deferral over a friendly chat every single time, and I’d take it without a second thought.
The First Call Window, and why it closes fast
I think of the days right after a crash as the First Call Window. It’s the stretch where the evidence is still fresh, the witnesses still remember, and the adjuster is still forming an opinion about you. Three things live inside that window, and once they’re gone they don’t come back.
Scene evidence. Traffic camera footage gets overwritten. Skid marks fade. A Metro Nashville police report captures the officer’s impression of fault, and that impression carries weight with insurers even when it isn’t the final word. If the report has an error in it, correcting the record early is far easier than arguing about it six months down the line.
Witness memory. The person who saw the whole thing from the sidewalk will give you a clean account this week. In three months they’ll give you a vague one, and a vague witness helps nobody but the other side.
Your own timeline. Tennessee sets a deadline for filing a personal injury lawsuit, and it’s not generous. The State of Tennessee publishes the statutory limits, and I’d rather you read them yourself than take a number from a stranger on the internet, including me.
A quick gut-check before you call anyone
- Do you have the other driver’s insurance information, or just a photo of a bumper?
- Is there a police report number, and have you actually read the report?
- Have you been evaluated by a provider, and is that visit documented?
- Has the adjuster already asked you for a recorded statement?
Two or more blanks means your file is thinner than theirs. That’s the gap worth closing first.
Why “I’ll just handle it myself” usually costs more
Plenty of claims settle fine without representation. Minor damage, clear fault, a cooperative insurer, and a few thousand dollars in medical bills. If that’s your situation, you might genuinely be better off handling it directly and keeping the full settlement instead of sharing it.
The math flips when the injury is bigger than it first appears, when fault is disputed, or when the at-fault driver carries the minimum coverage. Tennessee requires drivers to carry liability insurance, and the Insurance Information Institute maintains plain-language background on how auto coverage and claims actually work. Read enough of it and you’ll see the problem: minimum limits are small, and a serious injury blows straight through them. That’s when a case stops being a negotiation and starts being a fight over who else might be responsible.
Here’s the scenario I’d want you to sit with. Two drivers, same crash, same injuries. One gives a recorded statement on day two and mentions she feels “mostly okay.” The other says she’s still being evaluated and will follow up. Six months later, the second driver has a treatment record that tells a coherent story, and the first one has a recorded sentence the adjuster can quote back in every conversation. Same accident. Wildly different files.
How to pick someone, if it comes to that
Don’t hire the loudest billboard. Hire someone who asks about your treatment before asking about your case value. If the first question out of their mouth is about the accident and not about how you’re healing, that tells you something about how they’ll handle the next year.
Ask three things in the consult. Who actually works on my file, you or a case manager? What’s your fee structure, and how does it work if the case loses? How often will I hear from you, and through what channel? Vague answers to any of those are a reason to keep dialing.
Also worth checking: whether the firm has actually tried cases in the county where yours would be filed. Nashville’s courts have their own rhythms, and local familiarity isn’t a marketing line. The National Highway Traffic Safety Administration tracks crash trends nationally, but what happens in a Davidson County courtroom is a different kind of knowledge entirely.
What you should do today, not next week
Write down everything you remember about the crash in plain sentences while it’s fresh, including the weather, the time, and what you were doing in the thirty seconds before impact. That record is worth more than you think, and it costs you nothing but twenty minutes.
Photograph everything. The vehicles before they’re repaired, the intersection, your visible injuries if you have any. Then get evaluated by a provider and keep the paperwork in one folder, physical or digital, and put every adjuster call in a running log with the date and what was said.
And when the phone rings again, you’re allowed to say: I’m still being evaluated, I’ll follow up when I have more information. That sentence alone has protected more claims than any lawyer ever has.
If the file starts feeling heavier than you can carry, that’s the signal to bring in help, not a reason to panic. The drivers who come out best aren’t the loudest or the most aggressive. They’re the ones who kept their story consistent while everyone else was trying to write it for them. So: what’s in your folder right now, and what’s still missing?