Author: Jennifer Schaefer, MBA, ChFC, CLU, RHU, REBC, SHRM-SCP
Founder & CEO, JS Benefits Group | Forbes Business Council Contributor | Co-Host, Executive Leaders Radio
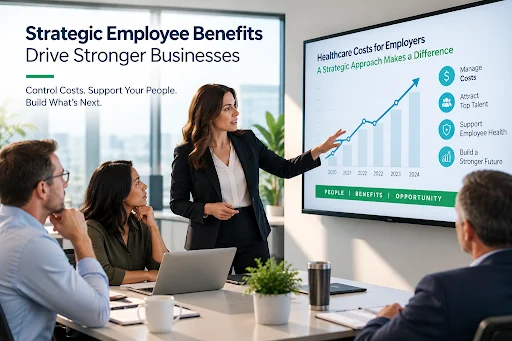
For many employers, health insurance renewal has become an annual exercise: review the new rates, make a few adjustments, and move forward with another year of coverage.
But rising healthcare costs are making that approach increasingly difficult to justify.
Instead of treating renewal as a routine administrative process, employers should use it as an opportunity to step back and evaluate whether their current benefits strategy is still delivering the right balance of cost, coverage and employee value.
A plan that worked well several years ago may no longer be the best solution for today’s workforce.
Start With the Current Plan
Before considering new insurance options, employers should understand how their existing plan is performing.
That means looking beyond the monthly premium.
Employers should evaluate employee contributions, deductibles, copayments, out-of-pocket maximums, prescription drug expenses, network structure and overall utilization.
It is also important to consider whether employees are actually using the benefits available to them.
A plan can appear competitive on paper while creating frustration for employees because of high out-of-pocket expenses, limited provider networks or a lack of understanding about how the coverage works.
Don’t Automatically Accept the Renewal
One of the biggest mistakes an employer can make is assuming that the renewal offered by its current carrier is the best available option.
The renewal should be treated as a starting point for analysis—not necessarily the final decision.
Employers can compare alternative carriers, funding arrangements and plan designs to determine whether there are opportunities to improve the overall value of the benefits program.
This is where an experienced employee benefits consultant can provide valuable perspective.
An independent evaluation can help employers identify opportunities that may otherwise be overlooked when the focus is limited to the renewal rate.
Consider Alternative Funding Strategies
Traditional fully insured plans remain appropriate for many organizations, but they are not the only option.
Depending on the size of the company, workforce demographics, claims experience and risk tolerance, employers may want to evaluate alternatives such as level-funded or self-funded arrangements.
Level-funded health plans have received increased attention because they can combine predictable monthly payments with features that provide employers with greater visibility into healthcare costs.
However, the right funding arrangement depends on the individual employer.
There is no universal solution, and employers should evaluate the financial structure, risk exposure and potential advantages before making a change.
Look at Employee Contributions
Healthcare costs are shared between employers and employees in many benefit programs.
When premiums rise, employers sometimes respond by increasing employee contributions or moving employees into plans with higher deductibles.
While these approaches may reduce the employer’s immediate expense, they can also affect employee satisfaction and retention.
A better approach is to evaluate the entire plan design.
For example, an employer may be able to adjust plan structures, funding arrangements or contribution strategies while maintaining a benefits package that remains attractive to employees.
The objective should be sustainable cost management—not simply transferring additional costs to employees.
Prescription Drug Costs Deserve Attention
Prescription drug spending has become an increasingly important component of healthcare costs.
Employers should understand how their pharmacy benefits are structured and whether the current arrangement provides appropriate value.
Questions around formularies, specialty medications, rebates, utilization and pharmacy benefit management can all affect the overall cost of a health plan.
Employers should therefore consider pharmacy costs as part of the broader healthcare strategy rather than evaluating medical insurance and prescription benefits in isolation.
Employee Communication Can Change the Value of a Plan
Even a well-designed benefits package can fall short if employees do not understand it.
Employees may not know how to compare plan options, when to use preventive care, how an HSA works or how their deductible and out-of-pocket maximum affect their expenses.
Clear communication can improve the employee experience and help workers make better decisions about their healthcare.
Employers should consider benefits education throughout the year rather than limiting communication to the annual open enrollment period.
Benefits Should Support Recruitment and Retention
Today’s employees evaluate more than salary when considering an opportunity.
Health insurance, retirement plans, flexibility, wellness programs and other benefits can influence how employees perceive an organization.
For small and mid-sized businesses, a thoughtful benefits strategy can be particularly important when competing with larger employers for qualified talent.
The goal is not necessarily to offer the most expensive benefits package.
Instead, employers should determine which benefits are most valuable to their workforce and build a sustainable strategy around those priorities.
Renewal Season Should Be a Strategic Review
A health insurance renewal should prompt employers to ask several important questions:
- Is the current plan still competitively priced?
- Are employees satisfied with the coverage?
- Are there opportunities to improve plan design?
- Are alternative funding arrangements appropriate?
- Are prescription drug costs being effectively managed?
- Does the benefits package support recruitment and retention?
- Is the company receiving enough strategic value from its benefits advisor?
The answers can help determine whether the organization should simply renew, negotiate changes or consider a completely different approach.
Employee benefits represent a significant investment for most employers. The companies that regularly evaluate that investment are better positioned to manage costs while continuing to provide meaningful benefits to their workforce.
About the Author
Jennifer Schaefer, MBA, ChFC, CLU, RHU, REBC, SHRM-SCP, is Founder & CEO of JS Benefits Group, an employee benefits consulting firm serving employers with health insurance, benefits strategy, cost containment, plan design and benefits administration. She is also a Forbes Business Council Contributor and Co-Host of Executive Leaders Radio.