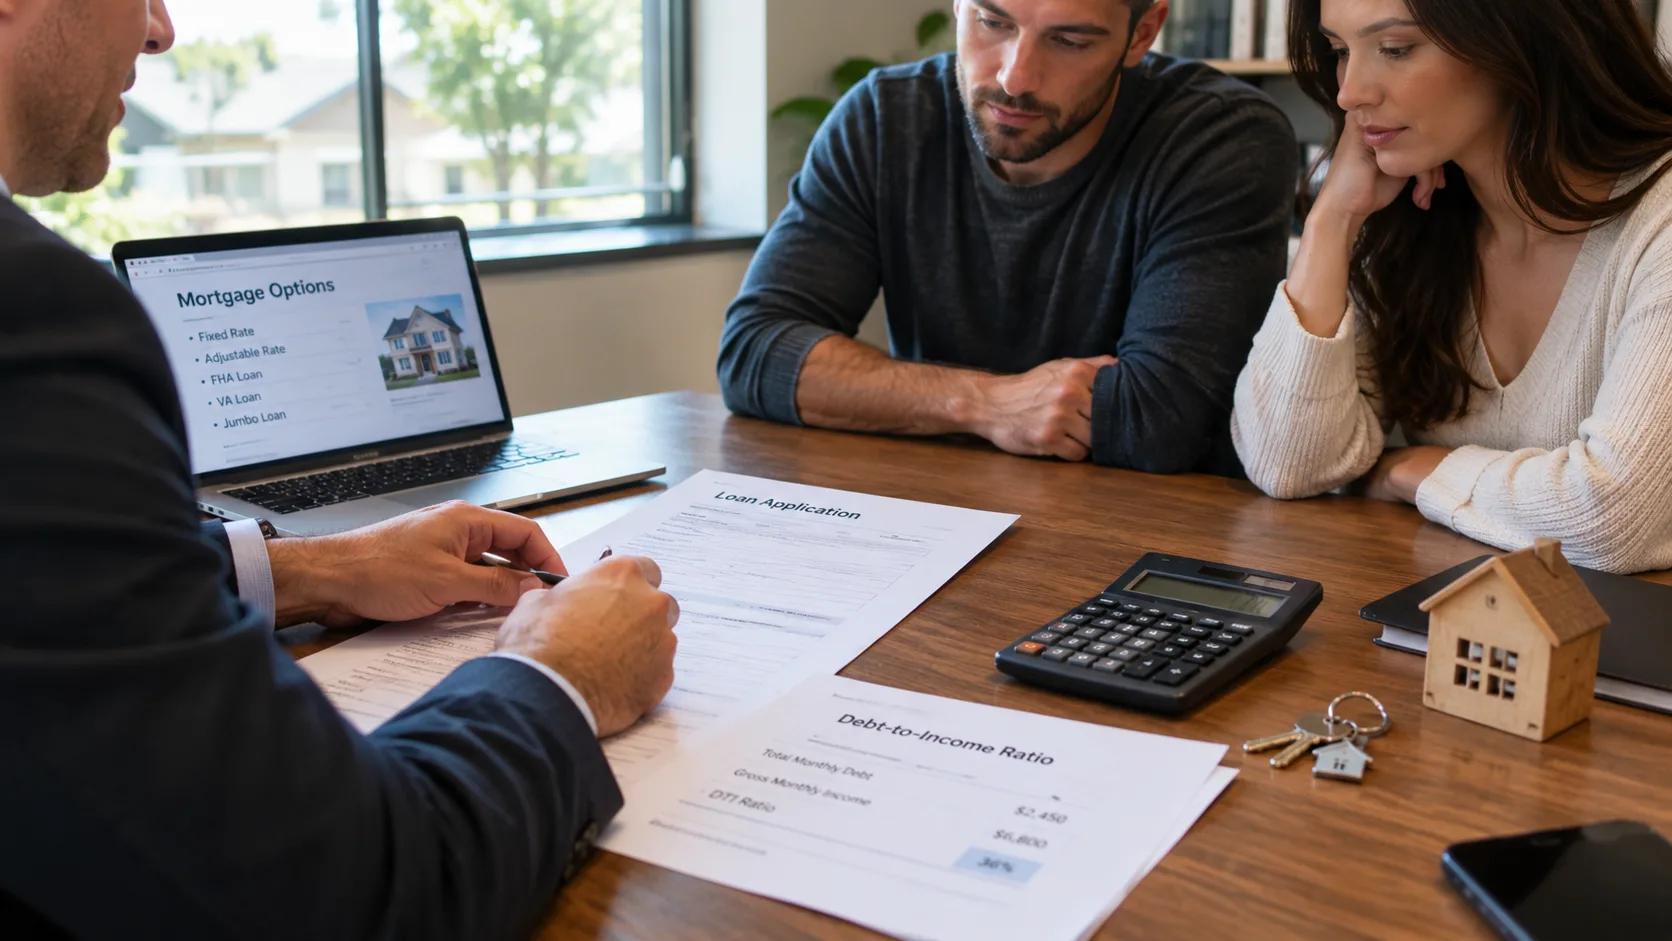
The debt-to-income ratio is one of the most important qualification metrics in mortgage and home equity lending. It measures the proportion of gross monthly income consumed by existing debt payments alongside the proposed new payment, and it affects not just whether you qualify but what rate you receive and how much you can borrow. These six ways it affects mortgage options explain why managing it before applying is one of the highest-return preparation steps available to borrowers.
- DTI Determines Basic Qualification
Most mortgage and home equity lenders set maximum DTI thresholds that applications must fall within to qualify at all. For conventional mortgages, the maximum qualifying DTI is typically 43 to 45 percent. For home equity loans, thresholds vary by lender but generally follow similar limits. A DTI above the lender’s maximum disqualifies the application regardless of how strong the credit score, the equity position, or the income level might otherwise be. The DTI is a binary threshold as much as a continuous variable in the qualification decision.
- DTI Determines the Maximum Loan Amount
Even within the qualifying DTI range, the maximum loan amount is constrained by how much additional debt service the borrower’s income can support while staying within the lender’s threshold. A borrower at 35 percent DTI before the new loan has meaningfully more borrowing capacity than one at 42 percent with identical income and credit, because the lower-DTI borrower can accommodate a larger payment before reaching the ceiling. This means two borrowers with the same income can access very different loan amounts based on their existing debt load.
- What Is the Best Home Equity Loan for Borrowers Managing DTI?
For borrowers whose DTI is a constraining factor, the best home equity loan is one that produces the lowest possible monthly payment for the needed loan amount, which points toward longer loan terms to spread the payment across more months. Achieve’s debt to income ratio for mortgage resource explains how DTI is calculated specifically for home equity loan qualification and how different loan term choices affect where the resulting DTI lands relative to the lender’s qualification threshold.
- DTI Affects the Interest Rate You Receive
A lower DTI signals more financial capacity and reduced repayment risk, which lenders reflect in the rate offered. The improvement in rate from reducing DTI from 42 percent to 35 percent, holding all other factors constant, reflects the reduced default risk that the lower debt burden represents. For borrowers near the higher end of the qualifying range, targeted debt paydown before applying can move the DTI into a tier that produces a meaningfully better rate on a substantial loan.
- Front-End and Back-End DTI Serve Different Purposes
Some lenders calculate two distinct DTI ratios: the front-end ratio that includes only housing-related payments such as mortgage principal, interest, taxes, insurance, and HOA fees, and the back-end ratio that includes all monthly debt obligations including car loans, student loans, credit cards, and the proposed new payment. For home equity loans, the back-end ratio is typically the governing metric because it captures the full picture of the borrower’s total debt service obligations and their overall financial load.
- Targeted Debt Reduction Before Applying Changes the Outcome
Paying off a small installment loan or reducing a credit card balance before applying for a home equity loan reduces the monthly minimum payments that count against the DTI calculation. The impact is most significant when a complete account is eliminated rather than when multiple balances are partially reduced, because eliminating a minimum payment removes it from the DTI calculation entirely rather than reducing it modestly. Identifying which existing accounts have the highest minimum payment relative to their remaining balance, and targeting those for payoff before the home equity application, produces the most efficient DTI improvement per dollar of debt paid.