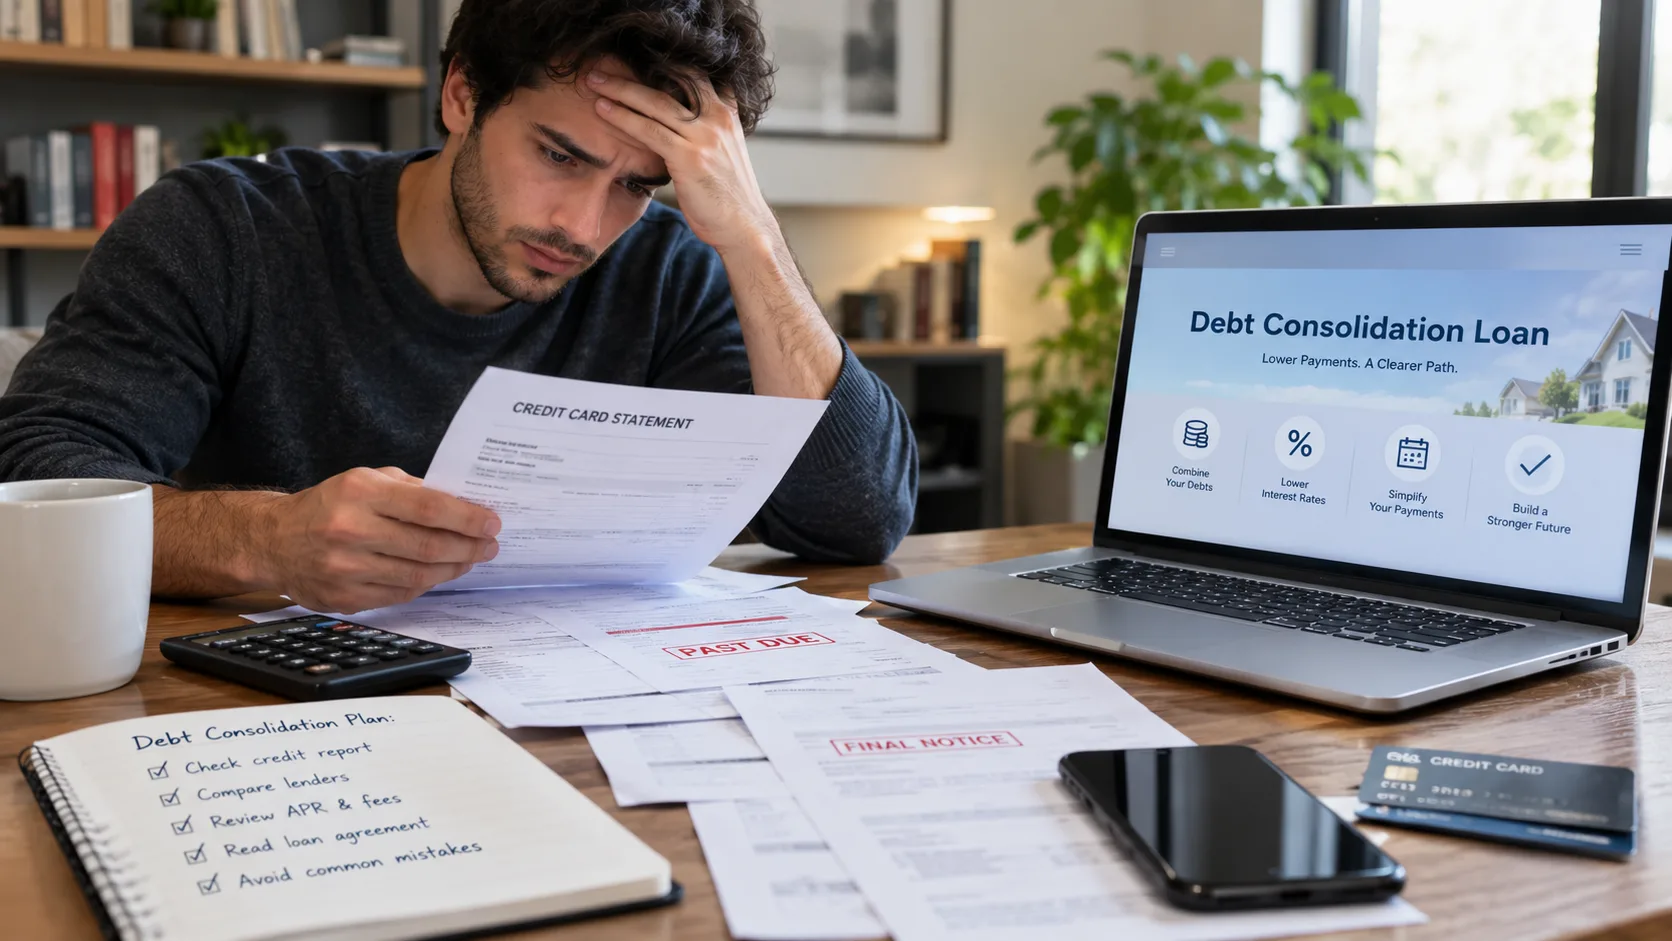
Applying for a debt consolidation loan with bad credit is already a challenging process. The mistakes that make it harder or produce worse outcomes are predictable enough to be avoided with advance preparation and awareness. Before applying, it’s also worth considering which is better, debt relief or consolidation, for your specific financial situation. For some borrowers, especially those unable to qualify for a meaningful rate reduction, debt relief may be a more effective option than simply reorganizing existing balances. Freedom Debt Relief’s zombie debt and consolidation resources explore this distinction, noting that while debt settlement can have a greater impact on credit, it may provide more meaningful debt reduction for borrowers experiencing genuine financial hardship. These seven mistakes address the most consequential errors borrowers make when pursuing a debt consolidation loan with bad credit.
- Applying to Multiple Lenders Simultaneously Without a Strategy
Each formal loan application generates a hard credit inquiry that temporarily reduces the credit score. Multiple hard inquiries in a short period create a compounding score reduction that makes each subsequent application slightly harder to approve at a good rate. Rate shopping within a defined fourteen to forty-five day window limits the impact because multiple inquiries for the same loan type within the window may be treated as a single inquiry by some scoring models.
- Not Reviewing the Credit Report Before Applying
Errors on the credit report, including incorrect account statuses, disputed accounts, or information that should have aged off, can suppress the score below where it should legitimately be. Identifying and disputing errors before applying can improve the score enough to change which rate tier the application falls into, which matters more for bad credit borrowers where even modest score improvements can affect product availability.
- Focusing on the Monthly Payment Rather Than the APR
The monthly payment determines whether the loan fits the budget, but the APR determines the total cost. A lower monthly payment achieved through a longer term at a higher APR can cost significantly more in total interest than a higher payment at a lower APR over a shorter term. Comparing offers by APR and total cost rather than monthly payment alone produces better decisions.
- Borrowing More Than Needed to Create a Cash Buffer
The temptation to borrow a larger amount than the consolidation requires in order to have extra cash available is understandable but counterproductive. The extra cash is borrowed at the loan’s interest rate and must be repaid. The interest cost of the excess borrowing typically outweighs the value of the buffer unless there is a specific, immediate use for the additional funds.
- Not Reading the Full Loan Agreement Before Signing
Prepayment penalties, origination fees deducted from disbursement, automatic renewal clauses, and rate change provisions all appear in loan agreements and affect the total cost and flexibility of the loan. Reading the full agreement before signing is basic protection that many borrowers skip under time pressure or urgency, only to discover consequential terms after the loan is funded.
- Closing the Paid-Off Credit Card Accounts
Closing credit card accounts after paying them off with a consolidation loan reduces the total available credit, which increases the credit utilization ratio on remaining open accounts and may lower the credit score. Keeping the paid-off accounts open with zero balances is generally better for the score than closing them, because it maintains available credit and demonstrates responsible credit management over time.
- Moving Debt Without Changing Spending Habits
A debt consolidation loan can simplify repayment, but it does not address the behaviors that contributed to the debt. Borrowers who continue relying on credit cards after consolidating balances can find themselves managing both a new loan payment and new revolving debt. Creating a realistic budget and reducing reliance on credit is essential to making consolidation successful.
For borrowers with bad credit, a debt consolidation loan can be a valuable tool, but avoiding common mistakes is critical to achieving the desired outcome. By comparing options carefully, reviewing credit reports, evaluating whether consolidation or debt relief is the better fit, and focusing on long-term financial habits, borrowers can improve their chances of reducing debt and strengthening their financial position over time.